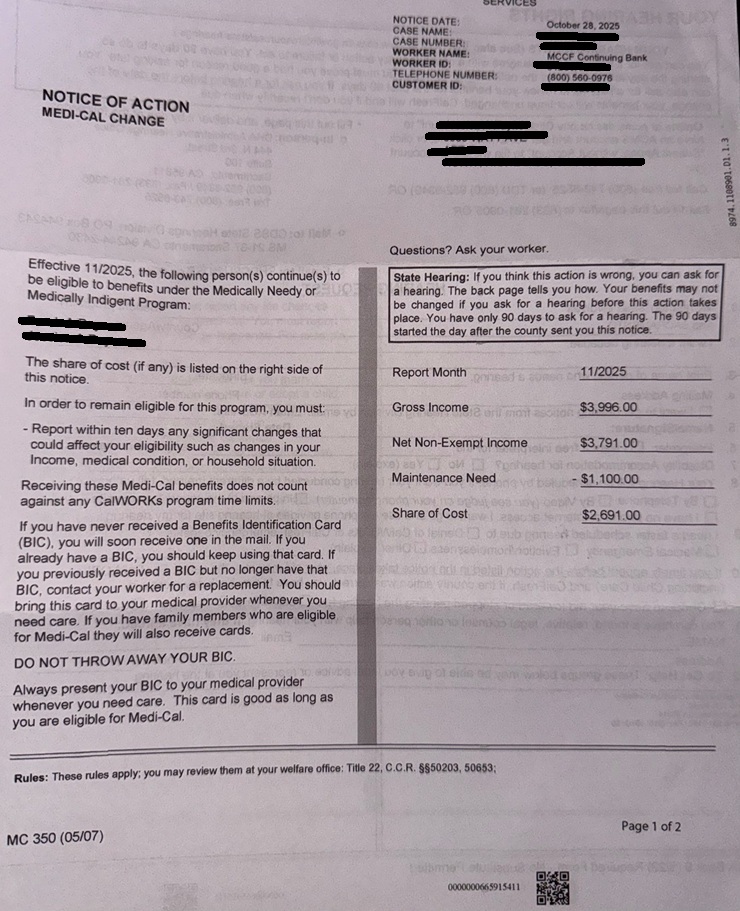
 Excerpt of Notice of Action
Showing Share of Cost

Calculate Insurance needed to
Eliminate Your Medi-Cal Share of Cost
Introduction to using Health Premiums to eliminated
Medi Cal Share of Cost
- Medi Cal imposes a share of cost (deductible) for those who get Medi Cal, but earn more than 138% of Federal Poverty Level, $1,836 in 2026 for a one person household.
- Thus, there is a complicated formula for how much you are over the income limit and how much you pay in Share of Cost the amount you pay, before Medi Cal pays anything that month, like a deductible. It's a REAL PROBLEM if you need an IHSS caregiver!
- The easiest way to figure out your share of cost, is to look at your notice of action then double check and find out with our CALCULATOR the share of cost and the amount of extra health coverage you need to eliminate it.
- your county Notice of Action
- Once you know the amount of coverage that you need, scroll down to get your coverage.
- If you have any questions or what more information:
- Email us [email protected]
- Set a Zoom meeting.
- We pride ourselves on not guessing as anything and having references for anything we say.
-
- Aged & Disabled and Medically Needy Medi-Cal Programs pdf Canhr 7/20/2026
- Are you able to work?
- Check out working disabled program 250%
- Medi-Cal Share of Cost 2026: What Changed (and What Didn't) Video Cookman Law
- 00:59 How Share of Cost works
- 04:17 Option 1: Dental, Vision, Medi Gap supplemental insurance
- FAQ's
- View our one page summary for professionals, social workers, attorneys, etc.
Monthly Health #Premium - Spenddown Needed
- $1–$84 per month:
Get quotes and enroll dental or vision plan
. - $85–$425 per month: Complete the
- AmFirst Maximum Care Application AmFirst offers premium choices within from $85 to $425
- Applications are processed quickly, and proof of coverage can usually be provided within 24 hours after you submit your application.
- Then you can easily upload (instructions) to BenefitsCal.com
- Just complete the one page application and email [email protected] to us.
- $426–$600 per month:
- A combination of the AmFirst Maximum Care application
- and another qualifying dental or vision premium
- $601 or more: The situation should be reviewed individually before applying. Send us the information below
- Medi-Gap premiums
- The monthly notice of action Share of Cost shown by your county.
- Your county and ZIP code.
- Whether you have Medicare Parts A and B and the premium amounts
- Any premiums you already pay for Medicare Part B, Part D, Medicare Advantage, Medi-Gap, dental or vision.
- Whether the problem concerns future months or previous months.
- Your Notice of Action Sample from the county
-
- Email Steve Your Share of Cost Information
- Our email is encrypted by PauBox
- Secure Upload
- Email Steve Your Share of Cost Information
After Enrollment:
Send Proof to the County
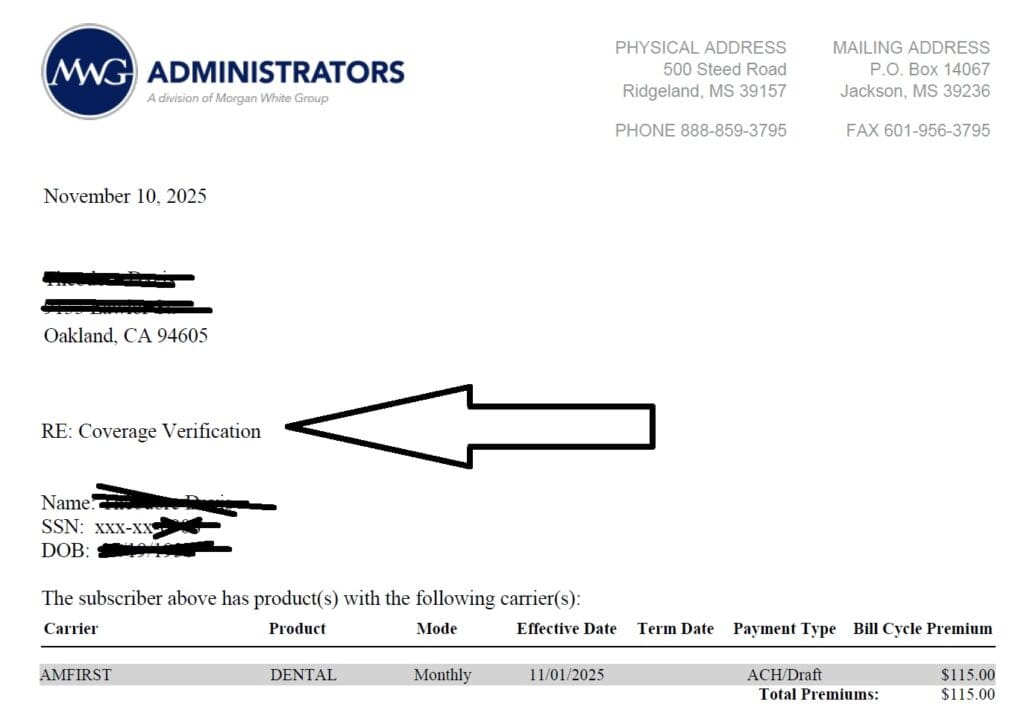
After approved enrollment, the county may request a proof-of-coverage letter, premium invoice, effective date and evidence that the premium was paid. Keep copies of everything submitted and follow up with your county worker.
See the complete proof and BenefitsCal document-upload instructions
.
Sample Proof of Dental Insurance for BenefitsCal
Share of Cost Testimonials
- “Medi-Cal reviewed my Mom’s case and eliminated her Share of Cost effective February 1. My family is very grateful that this issue was resolved in a very timely manner.” — Don V.
- “Eliminating her Share of Cost will allow her to stay living at our home longer, so it’s very wonderful.” — Mary
- “You are a wealth of knowledge, and I am so grateful to connect with you.” — Carie C.
- See additional Share of Cost comments and testimonials.
- See general client testimonials
- See this Reddit discussion about Share of Cost
References & Citations
- See California Code of Regulations, Title 22, §50555.2
- Determination of Medi-Cal Eligibility and Share of Cost Cornel Law
- DHCS Non-MAGI Medi-Cal Guide
- Center for Health Care Rights Plain English How to Eliminated Share of Cost
- CANHR Fact Sheet on Share of Cost
- What happens if you have two or more health or dental policies? Our webpage
- Videos
- Bet Tzedek legal aid
- More details on AmFirst Plan
- Morgan-White Brochures, Application, EOC, Forms & Guides
- in General – EOC Evidence of Coverage
- Chat GBT on Definition of UCR Usual Reasonable & Customary
Steve Shorr has specialized in California health insurance since 1975. There is no separate charge for assistance with an insurance application. Compensation is paid by the insurance company when applicable. Steve is an insurance agent, not a county eligibility worker, attorney or tax adviser.
This page provides general educational and insurance information. Medi-Cal eligibility and Share of Cost decisions are made by the county based on the individual facts and current program rules.
Medi-Cal Share of cost FAQ’s
California Medi-Cal Share of Cost FAQs
-
- What is Medi-Cal share of cost in California?
- Share of cost is the monthly amount a California Medi-Cal member must pay or incur in medical expenses before Medi-Cal begins paying for services.
- “Can dental insurance eliminate Medi-Cal share of cost?”“
- Yes
- Does Medi-Cal count Medicare premiums toward share of cost?”
- Yes
- “Can I keep my Medicare Advantage plan and still reduce share of cost?”
- Yes
- “Does paying for vision insurance reduce share of cost?”
- Yes
- Does share of cost reset every month in California?
- Yes. California Medi-Cal share of cost resets every calendar month.
- Is share of cost the same as a deductible?
- No. A deductible is usually annual and based on an insurance plan. Share of cost is monthly and based on income.
- Who has to pay share of cost in California?
- Typically seniors, individuals with disabilities, or people whose income exceeds standard Medi-Cal limits but still qualifies after deductions.
- Do prescription drugs count toward share of cost?
- Yes, prescription medications usually count toward share of cost in California.
- Can unpaid medical bills count toward share of cost?
- In many cases, yes — including certain unpaid bills from prior months.
- See our webpage on that.
- Can my share of cost change?
- Yes. Changes in income, household size, or deductions can change your share of cost.
- What about Estate Recovery? Can they take my home?
- Here’s our webpage on Estate Recovery
- Should I talk to an agent about share of cost?
- Absolutely. California Medi-Cal rules are complex, and a licensed agent can help identify better options. Also, ask your Social Worker and BenefitCal.com
- Email [email protected]
- Center for Health Care Rights – How to eliminate Share of Cost
- Here’s a website where you can get questions from the “community”
- What is Medi-Cal share of cost in California?
- What about a cancer or hospital indemnity plan?
- Short and honest answer: no — a cancer policy or hospital indemnity policy does not count as health insurance that lowers a Medi-Cal Share of Cost (SOC).Here’s the plain-English breakdown 👇
- Why these policies don’t reduce Share of Cost
- Medi-Cal only gives SOC credit for actual medical expenses or true health insurance premiums.
- Cancer and hospital indemnity policies are considered “supplemental” or “limited benefit” policies, not comprehensive health insurance.
- ❌ Premiums do not reduce countable income
- ❌ Benefits do not count as medical expenses to meet SOCWhat that means in practice
- They pay you cash, not doctors or hospitals directly
- The money can be used for anything (rent, food, gas, etc.)
- Because of that, Medi-Cal treats them as income-replacement or cash benefit policies, not medical coverage
So:
- Common examples that do NOT lower SOC
- Cancer-only policies
- Hospital confinement / hospital indemnity plans
- Accident-only cash benefit plans
- Critical illness lump-sum policies
- Even if the policy says “medical” in big letters — Medi-Cal looks at how it pays, not how it’s marketed.
What does lower Medi-Cal Share of Cost
These can reduce SOC if structured correctly:
✔ Major medical insurance premiums
✔ Certain dental insurance plans
✔ Vision insurance premiums
✔ Medicare premiums (Parts B, D, Medicare Advantage)
✔ Actual out-of-pocket medical bills- See FAQ on Adult Diapers below.
-
- It may work temporarily
- But it often gets reversed later — sometimes with back bills In some cases, long-term care insurance
The key rule: the expense must be tied directly to medical care or medical insurance — not cash benefits.
Important warning (this trips people up)
Some agents sell hospital indemnity or cancer plans claiming they lower Share of Cost.
That’s usually incorrect, and Medi-Cal caseworkers routinely deny those deductions.If someone is trying to use one of these policies to reduce SOC:
-
Bottom line
Cancer and hospital indemnity policies do NOT count as health insurance for lowering Medi-Cal Share of Cost.
If your goal is:
- Reducing SOC
- Qualifying for full Medi-Cal
- Coordinating with IHSS
…you need a policy designed specifically for Medi-Cal rules, not a cash-benefit plan.
If you want, tell me:
- County – Zip Code
- Approximate income sources
- Current Share of Cost
- Total Income
- Send all paperwork that you have.
This was Chat GBT – references on this page or our main share of cost page
Need Help With Share of Cost in California?
If you’re confused or frustrated by Medi-Cal share of cost, you’re not alone.
👉 Here’s the application with premiums up to $425
👉 Email us [email protected] please include all paperwork you have
- Can Medi Cal take our home when we pass away?
- See our webpage on estate recovery
- MSP Medicare Savings Program Medi Cal pays Part B premium
-
IRS Publication 502 pdf * html Medical & Dental #Expenses
-
Cal Fresh Rules on using Medical Expenses to lower income Cal Fresh.com
FAQ’s
- IHSS webpage
.
. - Question With SOC Share of Cost at 770.00 do I need to present the card at routine office visits, or present it only if medical expense is greater than 770.00. ?
.- Answer Yes, that way you get the Medi-Cal Negotiated Rate.
- Answer Yes, that way you get the Medi-Cal Negotiated Rate.
- Question If I have Share of Cost, can I get a Covered CA plan with Subsidies? APTC
.- Yes, since SOC is NOT minimum essential coverage so they can qualify for financial assistance through Covered California.
- Minimum essential coverage includes:
- Full-scope Medi-Cal programs, including the Targeted Low-Income Children’s Program (former Healthy Families program),43 Medi-Cal Access Program (MCAP – former AIM program), and Refugee Medical Assistance programs administered by Medi-Cal;44
- Medi-Cal Share of Cost programs and programs with limited scope of services such as Minor Consent), individuals enrolled in these programs can simultaneously enroll in a Covered California plan with advanced premium tax credits so long as they meet Covered California’s eligibility criteria.
- Medi-Cal only covers what Covered California does not, such as In-Home Supportive Services, adult dental, or long-term care, so individuals should check provider networks before picking a Covered California plan for most regular health services. Western Poverty Law *
- Plans with Covered CA subsidies? Get quote…
- Get Covered CA quotes.
.
- Minimum essential coverage includes:
- Yes, since SOC is NOT minimum essential coverage so they can qualify for financial assistance through Covered California.
- Question How does Medi-Cal share of cost work with Medicare Part D Rx Prescription coverage?
.- Answer If you are receiving both Medicare and Medi-Cal benefits, the Medicare Part D drug benefit will provide your prescription-drug coverage instead of Medi-Cal.
- Low-Income Subsidy (LIS) program, also known as the “Extra Help” program, will pay for part or all Medicare Part D drug-benefit plan premiums, depending on the plan in which you are enrolled. Learn more about the Extra Help program and the Medicare Part D drug benefit.
.
- Low-Income Subsidy (LIS) program, also known as the “Extra Help” program, will pay for part or all Medicare Part D drug-benefit plan premiums, depending on the plan in which you are enrolled. Learn more about the Extra Help program and the Medicare Part D drug benefit.
- Answer If you are receiving both Medicare and Medi-Cal benefits, the Medicare Part D drug benefit will provide your prescription-drug coverage instead of Medi-Cal.
- ..
- See situation # 16 above, it looks to me like you can get Medi Gap guaranteed issue.
- Here’s a video explanation of our research and answer to your question.
- You can also get dental & vision coverage.
- I will grant that it’s very confusing on the time periods that you can enroll or exit a Medicare Advantage Plan.
.
- Question Does veteran aid & attendance or death benefits as unearned income count towards share of cost?.
.- t seems like the best and understandable explanation
- Cen Cal Health FAQ
FAQ’s
Getting additional Insurance to #lower SOC Share of Cost
IHSS In Home Supportive Services
Please send us [email protected] all the paperwork from Medi Cal so that we can review it and see above for various plans once Medi Cal tells you how much you need to spend
When you’re dealing with Medi-Cal Share of Cost (SOC) in California, the key question is whether a payment is considered countable (unearned) income or excluded income under Medi-Cal rules.
Here’s how Veterans Aid & Attendance (A&A) is generally treated:
1️⃣ What Is Veterans Aid & Attendance?


Aid & Attendance (A&A) is an increased pension amount paid by the U.S. Department of Veterans Affairs to eligible veterans or surviving spouses who:
-
Need help with activities of daily living (ADLs), or
-
Are housebound, or
-
Reside in assisted living or a nursing facility
It is paid as part of a VA pension, not as a separate disability compensation program.
2️⃣ Is Aid & Attendance Countable for Medi-Cal Share of Cost?
✔️ In Most Cases — Yes, It Is Countable Income
Under California Medi-Cal rules:
-
VA pension payments (including the A&A portion) are treated as unearned income.
-
Unearned income counts toward the Medi-Cal Share of Cost calculation.
-
The full gross amount is typically included before standard Medi-Cal deductions.
So if someone receives:
-
$2,000/month in VA pension (including A&A),
that $2,000 is generally included as countable income when calculating Share of Cost.
3️⃣ How It Affects Share of Cost
For Aged, Blind, and Disabled (ABD) Medi-Cal:
Share of Cost formula (simplified):
Gross monthly income
– $20 general income disregard
– Maintenance Need Level (MNL)
= Share of Cost
Since A&A counts as income:
-
It increases gross income.
-
That usually increases Share of Cost unless offset by medical expenses.
4️⃣ Important Exception: Long-Term Care Medi-Cal
If someone is in a nursing facility under long-term care Medi-Cal, treatment can be slightly different:
-
Most income (including VA pension) goes toward the “patient pay amount.”
-
The individual keeps only a small personal needs allowance.
-
Spousal impoverishment rules may apply.
In those cases, VA pension is still income — but applied toward facility cost rather than traditional Share of Cost.
5️⃣ Can Aid & Attendance Ever Be Excluded?
There are limited circumstances where:
-
Certain VA reimbursements for medical expenses
-
Or unusual retroactive payments
might be treated differently.
But regular ongoing monthly Aid & Attendance pension payments are countable income for Medi-Cal purposes in California.
6️⃣ Practical Example
Let’s say a client receives:
-
$2,200/month VA pension with Aid & Attendance
-
No other income
Medi-Cal calculation might look like:
$2,200
– $20 disregard
– $600 (approx. Maintenance Need Level for 1 person)
= ~$1,580 Share of Cost
That means the client would need to incur $1,580 in medical expenses each month before Medi-Cal pays.
7️⃣ Strategic Planning Considerations (Where It Gets Interesting)
Because you work heavily with:
-
Medi-Cal Share of Cost strategies
-
Medical expense offsets
-
Long-term care scenarios
It becomes important to coordinate:
-
Proper documentation of recurring medical expenses
-
Adult diaper receipts
-
Home care invoices
-
Assisted living contracts
Those can reduce or eliminate Share of Cost each month.
Bottom Line
Veterans Aid & Attendance is generally countable as unearned income for Medi-Cal Share of Cost in California.
It increases gross income and therefore usually increases Share of Cost unless offset by allowable medical expenses.
If you’d like, I can:
-
Draft a short consumer-friendly explanation block for your website
-
Or create a compliance-oriented FAQ version with regulatory citations
-
Or map out how this interacts with spousal impoverishment rules
Just let me know which direction you want to take it.
Broker / Agent Reference — Broker Only
- The links and materials below are maintained as Steve Shorr Insurance's working broker reference library.
I appreciate your guidance on getting to zero share of cost, very informative! 🌟
Thank you for your help – I’ve spent years trying to figure this out and I’m glad you were able to help me.
Hi Steve,
Thank you for the nice presentation, [Loom explanation of an email] very helpful to see everything onscreen.
Best regards,
Leslie
Hi Steve,
Our zoom meeting this morning was very much appreciated.
I really benefited a lot from our discussion
Thank you very much for your assistance.
Sincerely,
Don V