When Can You Get a Medigap Plan With No Health Questions?
Guaranteed Issue
- California has several situations where you may be able to buy or change a Medicare Supplement / Medigap plan without medical underwriting. The two most common questions I get are:
- “Can I use the California Birthday Rule?” and
- “What happens if my Medi-Cal changes?”
- What to email me [email protected] :
- your date of birth,
- Medicare Part A and Part B effective dates,
- current plan name,
- Zip Code & county, and
- any notice you received from Medi-Cal, Medicare Advantage, or your insurance company.
Email Steve About My Medigap Rights |
Get Medigap Quote |
New to Medicare Part B —
Medigap Open Enrollment
Generally, this is the easiest time to buy a Medicare Supplement plan without medical underwriting.
You may qualify if:
- You are age 65 or older and newly enrolled in Medicare Part B; or
- You are under age 65, qualify for Medicare because of disability, and are newly enrolled in Medicare Part B.
When to apply
- Age 65 or older: California law provides a six-month Medigap open enrollment period beginning with the first month in which you are both age 65 or older and enrolled in Medicare Part B.
- Under age 65 due to disability: California provides a six-month open enrollment period after enrollment in Medicare Part B. If Medicare eligibility is determined retroactively, the six-month period can begin after notice of eligibility.
What guaranteed acceptance means
- The insurance company generally cannot deny your application because of your health.
- The company cannot charge you more because of your health status, claims history, or medical condition during the applicable open enrollment period.
- The exact Medigap plans available can depend on your age, when you first became eligible for Medicare, and the plans offered by that insurance company.
Information you may need
- Medicare Part A and Part B effective dates.
- Your Medicare Beneficiary Identifier (MBI).
- If under age 65, information about your current insurance coverage may also be requested.
Sources:
California Medigap Birthday Rule
You may qualify if:
- You already have a Medicare Supplement / Medigap policy; and
- You want to change to another Medigap policy with benefits equal to or less than the benefits in your current plan.
When to apply
- California law provides an annual open enrollment period lasting at least 60 days beginning on your birthday.
- Some insurance companies may allow you to submit the application before the protected Birthday Rule period begins.
What this means
- You may change insurance companies without medical underwriting if the replacement plan has equal or lesser benefits.
- The company cannot deny the application or charge you more because of your health during the protected period.
- Extra or innovative benefits such as dental or vision benefits generally are not used to decide whether one standardized Medigap plan has greater benefits than another.
What you may need
- Proof of your current Medicare Supplement plan.
- Your current Medigap ID card or other coverage documentation.
- Your date of birth and requested effective date.
Sources:
Employer or Retiree Health Coverage Is Ending
See also my web page — Medicare & Employer Coverage.
You may qualify if:
- You are enrolled in Medicare Part B and employer-sponsored health coverage is ending.
- This can include employer-sponsored retiree health coverage.
- It can include loss of eligibility because of divorce or death of a spouse.
- California law’s definition of employer-sponsored retiree health coverage also includes COBRA and Cal-COBRA coverage.
When to apply
- California provides a six-month Medigap open enrollment period following the applicable notice of termination or loss of eligibility — or the effective date if no notice was received.
Documentation
- Keep the employer, retiree plan, COBRA, or Cal-COBRA termination notice.
- If coverage is ending because of divorce or death, keep the notice showing the loss of eligibility and effective date.
- The exact documentation requested can vary by Medigap insurance company.
- COBRA and Medicare can be complicated.
Sources:
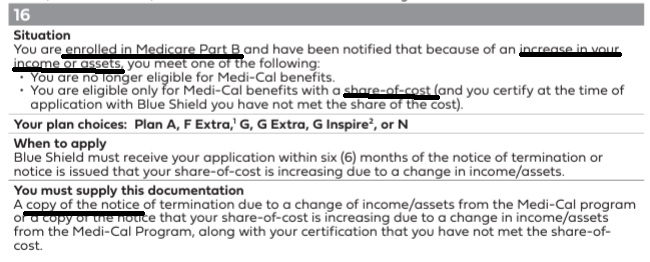
Medi-Cal Ends or Changes to a Share of Cost
See also my web page — Medi-Cal Share of Cost.
You may qualify if:
- You are enrolled in Medicare Part B; and
- Because of an increase in income or assets, you are notified that you are no longer eligible for Medi-Cal; or
- You become eligible for Medi-Cal only with a Share of Cost.
Important Share of Cost rule
- If you have a Medi-Cal Share of Cost, California law requires you to certify when applying that you have not met the Share of Cost.
When to apply
- California provides a special Medigap open enrollment right when Medi-Cal eligibility is lost or a Share of Cost is imposed because of an increase in income or assets.
- California Health Advocates states that there is a six-month period when a Share of Cost is first imposed or changes.
- Do not wait. Have the insurance company verify the applicable deadline using your actual Medi-Cal Notice of Action.
Documentation
- Keep the Medi-Cal Notice of Action showing the reason for the change.
- Keep the notice date, effective date, and Share of Cost amount.
- Do not discard the notice after the Medi-Cal change takes effect.
Sources:
Medicare Advantage Plan Ends, Leaves Your Area, or You Move
You may qualify if:
- Your Medicare Advantage plan terminates or stops offering coverage where you live; or
- You become ineligible for the plan because you move outside its service area; or
- Another qualifying involuntary termination applies.
When to apply
- The normal federal guaranteed-issue period generally begins before or when the Medicare Advantage coverage ends.
- California adds an additional 60-day open enrollment period after the federal period for people whose Medicare Advantage coverage is terminated. This can extend the protected period to 123 days after the MA coverage ends.
Documentation
- Keep the Medicare Advantage termination or service-area notice.
- Keep documentation showing your coverage termination date.
- If you moved, keep the notice showing that the new residence is outside the plan’s service area.
Sources:
You Tried Medicare Advantage, but didn’t like it
You May Have a Medigap Trial Right
Trial Right #1 — Medicare Advantage when first eligible for Medicare
- You joined a Medicare Advantage plan or PACE when first eligible for Medicare at age 65.
- You decide within the first 12 months that you want to return to Original Medicare.
- You may have a guaranteed right to buy a Medicare Supplement policy.
Trial Right #2 — You dropped Medigap to try Medicare Advantage
- You had a Medigap policy and dropped it to join Medicare Advantage for the first time.
- You decide within the first 12 months that you want to return to Original Medicare.
- You generally have a right to return to your former Medigap policy if it is still available from that company.
- If your former policy is no longer available, other guaranteed-issue Medigap choices may be available.
Documentation
- Keep proof of your former Medigap coverage.
- Keep the Medicare Advantage effective date and disenrollment documentation.
Sources:
Medicare Advantage Benefits, Premiums, Copays, or Treating Provider Change
California provides additional Medigap protections in certain situations, including:
- A Medicare Advantage plan reduces benefits.
- A Medicare Advantage plan increases premium or cost-sharing.
- A Medicare Advantage plan ends its relationship with a provider who is currently furnishing services to you, for reasons other than quality of care.
Important — this rule has additional conditions
- Your Medigap rights can depend on whether the Medicare Advantage company, its parent company, subsidiary, or affiliated network offers a Medicare Supplement plan.
- Where no affiliated Medigap is available, California law provides additional rights for specified premium or copay increases, benefit reductions, and termination of a treating provider.
- Enrollment with an unrelated Medigap company is generally limited to the Medicare Annual Election Period, October 15th to December 7th, except for the specified treating-provider situation.
Do not cancel your Medicare Advantage plan based only on this summary. Have the specific Annual Notice of Change, premium notice, or provider termination notice reviewed first.
Documentation
- Annual Notice of Change.
- Premium or copayment increase notice.
- Benefit reduction notice.
- Notice showing termination of a provider currently treating you.
Sources:
Other Medigap Guaranteed-Issue Situations
Federal and California law provide additional guaranteed-issue rights that are less common.
- Your Medicare Supplement insurer becomes insolvent or your Medigap coverage is otherwise involuntarily terminated.
- Your Medigap company substantially violates an important provision of the policy.
- The company or its representative materially misrepresented the Medigap policy when it was sold.
- Certain Medicare Cost, PACE, Medicare SELECT, or other Medicare health-plan coverage terminates.
- Certain employer plans stop providing benefits that supplement Medicare.
- Certain other exceptional circumstances recognized under Medicare law may apply.
If your coverage is ending unexpectedly, keep every termination letter and notice. A document that looks unimportant may establish the date and reason needed to prove guaranteed-issue eligibility.
Sources:
What If I Don’t Have a Guaranteed-Acceptance Right?
- You can still apply for a Medicare Supplement plan.
- Outside an open enrollment or guaranteed-issue period, an insurance company may require medical underwriting.
- Different insurance companies may have different health questions and underwriting requirements.
- Email us, [email protected] for a sample application
- One company may accept an applicant another company will not.
- Before answering health questions, first check whether one of the California or federal protections above applies.
If you qualify for a guaranteed-issue or protected open enrollment period, your health generally cannot be used to deny the Medigap coverage protected by that rule.
Email Steve — Do I qualify for guaranteed acceptance?
Sources:
Insurance Company Guaranteed-Acceptance Guidelines
The California and federal rules above apply broadly, but each insurance company has its own application, documentation procedures, plan availability, and underwriting instructions.
- Blue Shield of California — Guaranteed Acceptance Guide MSP17149_1025 — I use this guide frequently because it is relatively easy to review by situation.
- Anthem Blue Cross — email Steve for current guaranteed-acceptance guidelines.
- AARP / UnitedHealthcare — email Steve for the current company guidelines.
Important: A company’s underwriting guide does not replace California or federal law. It shows how that company currently handles applications and documentation for the applicable rules.

- Get Quotes for Medi Gap Quotit
- Introduction to #MediGap Medicare Publication 02110
- MORE Information and Links
- Matrix - Spreadsheet of what Medicare Pays, Medi Gap pays, Medicare Advantage and what little you pay
#Guaranteed Acceptance Guides Medi Gap
- Blue Shield
- Blue Cross Guaranteed Guide CA Scroll down to page 7 Guaranteed Issue Section of the application
- United Health Care – Email us [email protected]
- Get more detail compare contract explanation at:
- Legislation to make Medi Gap easier to get into, if Medicare Advantage cancels or something >>> Think Advisor *
FAQ’s just turned Age 65 or newly enrolled in Part B”
- Hello – I just signed up for Medicare Part B using the current GEP General Enrollment Period Timetable and Guaranteed Issue Availability Since I relied on Cobra coverage, which isn’t considered Employer Coverage, I will be subject to a penalty Am I entitled to a guaranteed issue Medigap policy, and how soon before July do I have to obtain the policy?
- Yes, under situation # 1 above, you are entitled to guaranteed issue Medi Gap as it says 65 and enrolled in Part B!
- I grant you, I don’t like the wording… but I’ve checked with the carriers and have actually had coverage issued.
- I suggest you enroll, as soon as you get confirmation that Part B has been approved!
- See our Medi Gap Pages for Blue Cross , UHC United Health and Blue Shield,
- There is no extra charge for our expertise. You can enroll online or we can help you in a Zoom meeting.
- 1 Is it true that one has to sign up for a Medigap plan within 6 months of starting Medicare?
2 I will be starting in June, [that’s when I turn 65] so can I wait until November to sign up for a Medi-gap plan ? (to save money?)- 1 Yes, see above for details
2 Yes, if I’m counting on my fingers correctly. Your six months would start in June.- I do not recommend that you wait. If this is your plan, you might be better off finding another agent to help you. Purposely waiting can only lead to a malpractice claim and a major hurt to your pocket book. If one knew when they were going to have a claim or be in an accident, they just wouldn’t leave the house that day.
- Will your next question be, how long can you wait to sign up for Part B?
- 3 months after the month you turn 65. That would save you $134/month.
- If you are on a budget, how about Hi F? You pay the first 2k of bills, not paid by Medicare A or B and you save around $100/month on premium. Get quotes and enroll online.
- 1 Yes, see above for details
FAQ’s on “Birthday Rule”
Effective Date of new policy?
- California’s Medi Gap birthday rule DOES NOT APPLY for Plan C Medicare Advantage
- MAPD Changes can be made only during end-of-year period AEP October 15 through December 7th or a special enrollment MAPD Open & Special Enrollments
- #tobacco usage? It’s guaranteed issue isn’t it?
- CA Insurance Code 10192.11. (h) (1) … annual open enrollment period … During this open enrollment period, no issuer that falls under this provision shall deny or condition the issuance or effectiveness of Medicare supplement coverage, nor discriminate in the pricing of coverage, because of health status, claims experience, receipt of health care, or medical condition of the individual if, at the time of the open enrollment period, the individual is covered under another Medicare supplement policy or contract.
- So, is tobacco usage protected under health status?
- Resource Brokerage.com Central States Indemnity agent underwriting guide – CA requires Tobacco usage question even in Open Enrollment or Guaranteed Issue
- (24)(36) “Health status” means the determination bya carrier ofthe past, present, or expected risk of an individual or the employer due to the health conditions of THE INDIVIDUAL OR the employees of the employer.
(24.5) (37) “Health-status-related factor” means any of the following factors:- (a) Health status;
(b) Medical condition, including both physical and mental illnesses;
(c) Claims experience;
(d) Receipt of health care; Ch. 217 Insurance 913
(e) Medical history;
(f) Genetic information;
(g) Evidence of insurability, including conditions arising out of acts of domestic violence; and
(h) Disability. Colorado.Gov
- (a) Health status;
- One might also check with https://cahealthadvocates.org/ for their research, which isn’t answered on their website
- d. Tobacco Use – If a carrier reflects tobacco usage in the calculation of rates, then it shall do so according to the following requirements:
- Confidential Agent Manual 2017
- Members who have smoked tobacco cigarettes or used any tobacco product at any time within the past 12 months will pay the tobacco rate. Non-tobacco rates apply to all applicants who meet open enrollment or guaranteed issue requirements.
- Obamacare/ACA doesn’t allow health questions, but it does allow tobacco usage to be surcharged 50%. CA though doesn’t allow the surcharge.
- If I sign up for Plan G, Hi-F Medicare Supplement plan now, can I easily switch to a regular Plan F or something higher later?
- The birthday rule above used to only allow you to change from one plan to another of the same or lesser value on your birthday. See the Medi Gap Plans A – N Chart.
- Underwriting Holiday or Freedom to Switch may allow you to do that.
- If you are healthy when you want to make a change, you can do that anytime. Here’s typical underwriting questions.
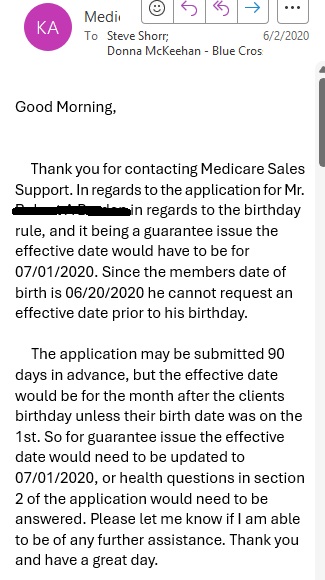
Transfer Application
No need to fill out Health Questions
When you fill out the transfer application under the birthday rule, whether ONLINE or Paper, check off the equal or lesser plan that you want.

Then put down the rule – situation # for the Insurance Company that you are using.

When you get to the Statement of Health, you don’t have to fill out any questions.
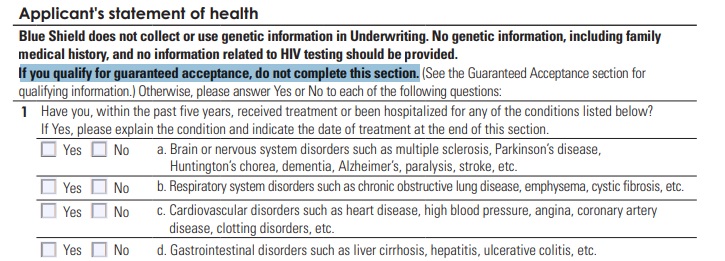
While these pictures are from the Blue Shield application, the general principles apply to all Insurance Companies.
Blue Shield of California Authorized Agent - Broker
When you enroll in Medi Gap beyond age 65 for Part B as you had
Qualifying #Employer Coverage
Termination of Employment or Retirement Plan
You have the right to purchase a Medi-gap policy for 6 months if your, your spouse’s or a family member’s current employment or retirement plan coverage terminates, or you lose your eligibility due to divorce or death of a spouse or family member.
The 6-month period to apply for a Medigap policy starts on the date you receive notice that your health benefits will end. If you do not receive advance notice, the 6-month period starts the date the benefits end or the date of your first denied claim. This protection of California law applies whether your group health benefits were primary or secondary to Medicare.
Our webpage on the pros & cons of Employer Coverage vs Medicare
Loss of COBRA or Cal Cobra
You are also entitled to this protection when you become eligible for COBRA (Our webpage on COBRA) or have used up all your COBRA benefits. It does not apply if you stop paying COBRA premiums before you use all your benefits. COBRA benefits are always secondary to Medicare benefits unless you have ESRD Renal Kidney Failure and are in a 30-month coordination period. For more information on COBRA, see Medicare & Other Health Insurance. CA HealthCare Advocates *
COBRA and Medicare are VERY VERY confusing. Double check with us [email protected] on your specific situation!!!
Situation 4 From Medi Gap Guaranteed Issue Guide
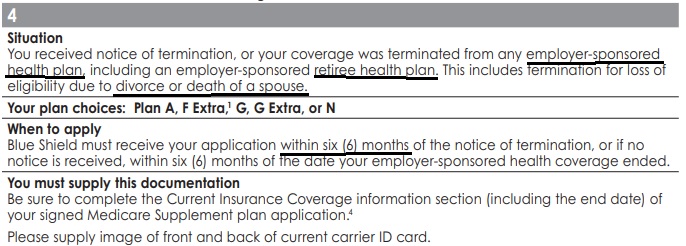
You received notice of termination, or your coverage was terminated from any employer-sponsored health plan, including an employer-sponsored retiree health plan. This includes termination for loss of eligibility due to divorce or death of a spouse.
Situation 11 from Medi Gap Guaranteed Issue Guide
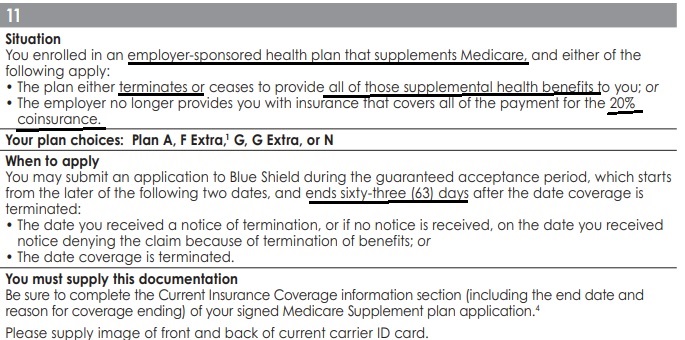
- You enrolled in an employer-sponsored health plan that supplements Medicare, §419 (e) Welfare Benefit Plans and either of the following apply:
- The plan either terminates or ceases to provide all of those supplemental health benefits to you; or
- The employer no longer provides you with insurance that covers all of the payment for the 20% coinsurance.
- Why is there Both situation 4 and 11?
- I asked and was told # 11 applies to §419 (e) Welfare Benefit Plans
- Learn More about not enrolling in Part B if you have employer coverage
- See our main page on loss of employer coverage
FAQ Loss of Employer Coverage
FAQ’s
Loss of Employer Coverage
- Where can one find the Official list for Medicare Advantage Plans, being as they differ from Medi Gap Plans?
- Are Medigap policies written during the 8-month Special Enrollment Period issued subject to the same terms as terms, with regard to pre-existing conditions, as those written during the Initial Enrollment Period?
- The waiver of Pre X would be the same. Situation # 4 above says the enrollment period is 6 months. It gets QUITE confusing with different rules for different enrollments… Part B Outpatient, Part D Rx, Medicare Advantage, etc. One has to check each option with a fine tooth comb!
- See links above to enroll online with Blue Cross and Blue Shield, email us for UHC United Health Care
- Here’s our scheduler to set a zoom meeting with screen sharing. set-a-meeting/
- See links above to enroll online with Blue Cross and Blue Shield, email us for UHC United Health Care
- The waiver of Pre X would be the same. Situation # 4 above says the enrollment period is 6 months. It gets QUITE confusing with different rules for different enrollments… Part B Outpatient, Part D Rx, Medicare Advantage, etc. One has to check each option with a fine tooth comb!
- I already have Medicare A and want part B. I am covered by a federal employee health plan (FEHB). Medicare (SSA) says I need to have a form filled out by my company president to verify employment- my W2 and tax form indicating coverage is not enough. Online it says my Medicare part B won’t start until July.
- We will answer that question on our page about if you have employer coverage – do you have to enroll in parts A, B & D?
- If you want more information and details – Please send a copy of your termination notice and if at all possible, all documents from your Employer’s Health Plan. Don’t hold back. We need to see if your under situation 4 or 11.
- Did the employer plan supplement Medicare or not?
- If one gets terminated from their spouses retiree benefits plan when the spouse passes away is there a guaranteed enrollment period into Medi Gap and how does it work?
- Yes. See situation # 4 above.
- If you cancel your Part B, then you to reinstate Part B later will you have guaranteed issue rights for Medi Gap?
- Excerpt from Medicare Medi Gap Guide # 02110 * Medicare.Gov *
- It’s also important to understand that your Medi gap rights may depend on when you choose to enroll in Medicare Part B. If you’re 65 or older, your Medigap Open Enrollment Period begins when you enroll in Part B and it can’t be changed or repeated.In most cases, it makes sense to enroll in Part B and purchase a Medi gap policy when you’re first eligible for Medicare, because you might otherwise have to pay a Part B late enrollment penalty and you might miss your Medi gap Open Enrollment Period. However, there are exceptions if you have employer coverage.
- From prior conversations and emails, you’ve stated that you have an application pending for Part B, but have not been enrolled. I’d check and see if you can get the application cancelled, as if you never asked to be enrolled in Part B.
- Either you or I can write to HICAP – CA Advocates and see what light they can put on the subject.
- This may be a question to learn when you got Part B and if you can get guaranteed issue at a later date…
- Excerpt from Medicare Medi Gap Guide # 02110 * Medicare.Gov *
Employer loss of Coverage Guaranteed Issue
CA Insurance Code §10192.11
(e) (1) An individual enrolled in Medicare Part B is entitled to open enrollment described in this section for six months following:
(A) Receipt of a notice of termination or, if no notice is received, the effective date of termination from any employer-sponsored health plan including an employer-sponsored retiree health plan.
(B) Receipt of a notice of loss of eligibility due to the divorce or death of a spouse or, if no notice is received, the effective date of loss of eligibility due to the divorce or death of a spouse, from any employer-sponsored health plan including an employer-sponsored retiree health plan.
(C) Termination of health care services for a military retiree or the retiree’s Medicare eligible spouse or dependent as a result of a military base closure or loss of access to health care services because the base no longer offers services or because the individual relocates.
(2) For purposes of this subdivision, “employer-sponsored retiree health plan” includes any coverage for medical expenses, including, but not limited to, coverage under the Consolidated Omnibus Budget Reconciliation Act of 1985 (COBRA) and the California Continuation Benefits Replacement Act (Cal-COBRA), that is directly or indirectly sponsored or established by an employer for employees or retirees, their spouses, dependents, or other included insureds.
Be careful and double check – COBRA might not get you out of the Part B Late Enrollment Penalty!
- Interaction between COBRA and Medigap Guaranteed Issue Requirements in Situations Involving Termination of Employer Group Coverage
FAQ’s
MAPD Trial Period – Come back to Medicare and Medi-Gap”
- Question I enrolled in a Medi-Gap plan, last year when I turned 65. If I enroll in a Medicare Advantage plan, can we go back to our Medi Gap plan anytime or do we have to wait for Open Enrollment, 10.15 to 12.7 annually?
. - Answer If you cancel the MAPD plan within 12 months, you can go back to your Medi Gap plan.
- If you stay in the MAPD plan longer than a year, you would have to meet underwriting – health questions to get a Medi Gap policy. There might be some Insurance Companies more liberal, but the law doesn’t require it.
- Check with us when you’re ready to change. Sometimes there are “limited time” special offers, underwriting holidays – freedom to switch
- The Open Enrollment Period is only for MAPD and Part D Rx guaranteed sign up, switching plans or going back to original medicare, Parts A & B.
- Again, if you are in a MAPD plan longer than a year, it’s not guaranteed issue to get your Medi Gap plan back
- The Trial right is only for the first time you drop Medi Gap to try MAPD
.
- Question If I understand it, this benefit – Right to get a Medi Gap Plan occurs because there is a “trial” period for MA in certain cases. However, those cases don’t seem to include the case in which MA was obtained upon returning from overseas. What am I missing?
.- Answer Federal Guaranteed Rights to get Medi Gap is shown in Publication 02110 above
- You are right, in your case, as you are not currently living in the USA you wouldn’t be joining at age 65, since you are not resident in any MAPD Service area.
- Check the other guaranteed issue rights, like if there is a change in premium or benefits.
- Blue Shield is liberal… Plus CA has or may have more liberal rights for guaranteed issue into Medi Gap Check out situation 14 Check out Situation # 17 if you get another company who changes benefits or premium 15% or more…
- One must read all these rules at least 3 times and then when you think you understand it, read it again. Justice Felix Frankfurter
.
- Question Do I understand correctly that a MAPD plan that was guaranteed issued, as I was living overseas and returned to USA as we discussed in this can be reverted to original Medicare + Medigap also on a guaranteed issue basis after a year?
- Answer Yes. That’s what this whole section is about. See above for details and explanation. If you have further questions, email us
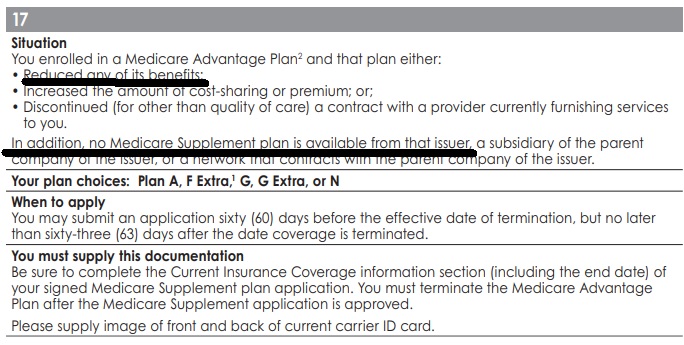
Renewal Medicare Advantage Plan offers #less benefits or raises premium
Excerpt from Blue Shield
Situation # 17
- MAPD plan ends – Medi Gap in CA purchasable till May 3rd CA Health Care Advocates.com
- ca health advocates.org/medicare-advantage-plan-ended-you-have-a-guaranteed-right-to-medigap/ till May 2026
- CA Insurance Code §10192.12 (D)
- (i) The Medicare Advantage plan in which the individual is enrolled reduces any of its benefits or increases the amount of cost sharing or premium or discontinues for other than good cause relating to quality of care its relationship or contract under the plan with a provider who is currently furnishing services to the individual.
- An individual shall be eligible under this subparagraph for a Medicare supplement policy issued by the same issuer through which the individual was enrolled at the time the reduction, increase, or discontinuance described above occurs or, commencing January 1, 2007, for one issued by a subsidiary of the parent company of that issuer or by a network that contracts with the parent company of that issuer.
- If no Medicare supplement policy is available to the individual from the same issuer, a subsidiary of the parent company of the issuer, or a network that contracts with the parent company of the issuer, the individual shall be eligible for a Medicare supplement policy pursuant to paragraph (1) of subdivision (e) issued by any issuer, if the Medicare Advantage plan in which the individual is enrolled does any of the following:
- (I) Increases the premium by 15 percent or more.
- (II) Increases physician, hospital, or drug copayments by 15 percent or more.
- (III) Reduces any benefits under the plan.
- (IV) Discontinues, for other than good cause relating to quality of care, its relationship or contract under the plan with a provider who is currently furnishing services to the individual.
- (ii) Enrollment in a Medicare supplement policy from an issuer unaffiliated with the issuer of the Medicare Advantage plan in which the individual is enrolled shall be permitted only during the annual election period for a Medicare Advantage plan, except where the Medicare Advantage plan has discontinued its relationship with a provider currently furnishing services to the individual. Nothing in this section shall be construed to authorize an individual to enroll in a group Medicare supplement policy if the individual does not meet the eligibility requirements for the group.
- I don’t see that the Federal Law per the Medi Gap Guide has this rule.
- – Have us or your agent review bullet points 7 & 8 in confidential agent manual.
- When a Medicare Advantage Plan Does Not Renew Its Contract * California Health Care Advocates * Medicare Advocacy.org
Under 65 – Medi Cal Changes
I have Medicare and I’m #under 65,
What Medi Gap or Medicare Advantage Plans can I get?
If you are under 65 and have Medicare due to a disability, SSDI, SSI? you can get Part D Rx, Medicare Advantage and Medi Gap plans, guaranteed issue, no medical questions asked, in California by enrolling when you are first eligible or in the case of Part D & Medicare Advantage, at Open Enrollment 10.15 to 12.7 each year. Other states may differ, learn more CA Healthline 1.4.2016.
When you turn 65, that gives you an additional time to enroll in a Medicare Supplement plan at LOWER rates.
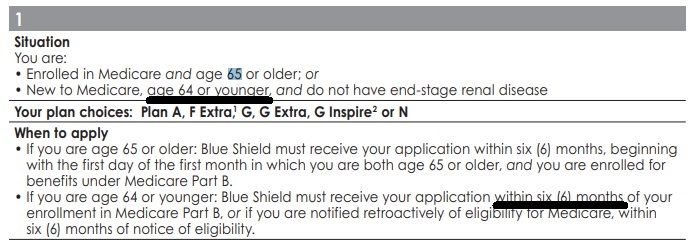
See Medicare and You # 10050 and each Insurance Companies Web Page (see menu above) for details, brochures, enrollment forms and rates.
Please email us, [email protected] if you want more personalized attention.
FAQ’s, Resources & Links
Special Enrollment times for Medicare Advantage
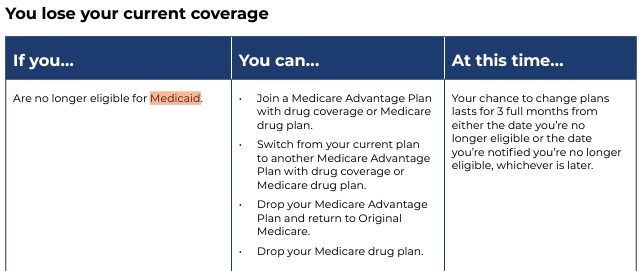
Guaranteed Right to get Medi Gap if your #Medi-Cal benefits change…
- You can deduct the cost of that policy or product and that may help them get under the strict income limit in the Aged & Disabled Federal Poverty Level FPL and Blind FPL programs. See above, you must have original Medicare, A & B not Medicare Advantage. Learn More Medicare.gov
- You may be able to drop Medicare Advantage – but that is up to YOU! We are not telling you to do it!
- If your purchase private health insurance with coverage that duplicates Medi-Cal coverage, the private health coverage would be billed first and then Medi–Cal would pay for the services it covers after the private health carrier pays or denies a claim. Our webpage on Dual Coverage * Western Center Law & Poverty Guide for Low Income Americans * CA Code of Regulations 22 § 50555.2 * Health Care Rights.org *
Guaranteed Issue Rules to Get Medi Gap
- Here’s a video explanation of our research on how one might get Medi Gap even if they are not healthy. If you have a Medicare Advantage plan, see also Situation # 17
- Visit our Medi Gap Guaranteed Issue Page
- Problems getting Medi Gap if you have full benefits Medi Cal?
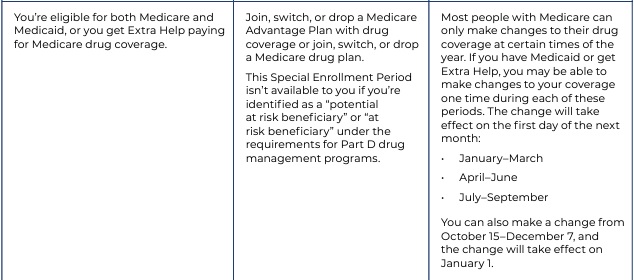
Right to Opt out of Medicare Advantage
FAQ under 65
FAQ’s “Under 65 disabled & Medicare Qualified”
- I have been trying to get a Medicare supplement for two years. NO one will give me one. I get denied for anything, for an H. Pylori infection. Every company I apply with denies me. I was born in 1957 and have Medicare but no company will give me a supplement. They all want to give me prescription drug plan while denying the medical plan. I live in California.
- How about Medicare Advantage at the next Open Enrollment? Medicare Advantage is guaranteed issue, while Medicare Supplements where you can go to any doctor or hospital that accepts Medicare is not. Check out our page on when Supplements are guaranteed issue. See also the subpage where if you take a Medicare Advantage Plan and don’t like it, you can then get a supplement. Let’s talk privately about some companies that have an unofficial practice of being more liberal…
- Please note that Medicare Supplements are not like Obama Care, there is no right to guaranteed issue, any time. Even Obama Care has certain open enrollment periods. See our page on Medical Loss Ratio, the Insurance Companies take in a small premium…from lots of people, but have to be able to pay all claims from all policy holders. See also the new page – under construction we are building on Donald Care. It appears that many of our leaders don’t understand medical underwriting and the law of large numbers.
- Hi. I’m looking for the best price on a Pre-65 Plan N supplement. We have Anthem at $249/month. My wife is on Social Security Disability. Birthdate: 10/25/1954. The price for Anthem started at $174 and after six months they raised it to $249. Any possibilities we should look into?
- I’ve responded to you privately. Use the menu above to check out other companies for Medi-Gap… but there may be a problem with Guaranteed Issue. In October there is Medicare Advantage.
Steve talks about Plan G & Extra – Innovative VIDEO
What Plan G pays in addition to Medicare Parts A & B
- Check our Carrier Pages for the latest Info
- Anthem Blue Cross
- Blue Shield – Medi-Gap
- Email us [email protected] for UHC United Health Care information
- Plan G vs Plan F much better pricing our webpage
- Medicare Advantage and Part D Rx enrollment periods – THEY ARE NOT THE SAME AS Medi GAP! our webpage